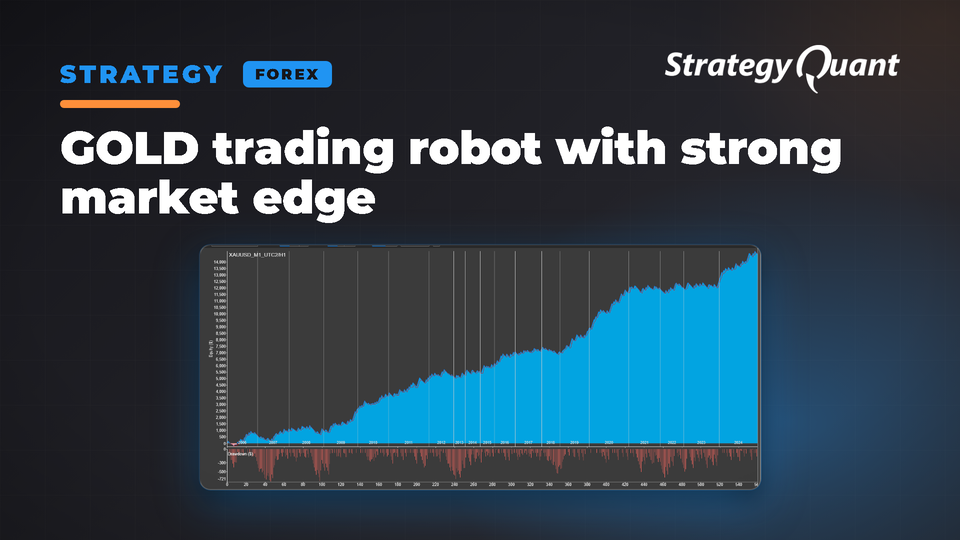
Swing trading strategy for XAUUSD H1 using breakout and linear regression with 1:3 risk/reward ratio. Backtested with Monte Carlo simulations, slippage tests, and out-of-sample validation.
This Swing Simple strategy for GOLD H1 timeframe. This strategy uses RRR 1:3. It was build by following this free workflow from AlgoLab. Strategy passed by these robustness tests Monte Carlo simulations, slippage, 2 Out Of Sample data test, 2 different timeframes. With this custom project, you can start easily building strategies based on breakout and swing logic. Strategy was built on EST+7 timezone.
Strategy Equity:
Parameters Monte Carlo Simulations:
Description of the strategy logic:
Long (Buy) Entry:
The high price from two bars ago is higher than the low of the daily chart for three consecutive bars.
The opening price from three bars ago is below a 14-period linear regression line.
If these conditions are met, a long trade is opened at the highest price within the last 610 bars.
The order is valid for 9 bars, with a stop loss of 805 pips and a profit target of 2350 pips.
Short (Sell) Entry:
The open price from two bars ago on the daily chart is higher than the high of the main chart for six consecutive bars.
A SuperTrend indicator is higher than the open price from three bars ago, also for six bars.
The trade is opened at the lowest price within the last 615 bars.
The order is valid for 4 bars, with a stop loss of 865 pips and a profit target of 2255 pips. If the trade is still open after 36 bars, it will automatically close.
How to backtest strategy in StrategyQuant
1) Load strategy to the retester
2) If you do not have downloaded data, you have 2 options, you can just apply the config from the strategy and add the missing symbol or import common tickers from this config file
3) Download the data for XAUUSD using selected update only in data manager
Join Algolab: A Free Online Course on Algorithmic Trading with StrategyQuant
Are you interested in learning how to build powerful trading strategies for indices? Join our free online Algolab course on the StrategyQuant YouTube channel and dive into the world of algorithmic trading!
• How to create automated trading strategies step-by-step using StrategyQuant.
• Develop strategies for indices using proven templates and logic.
• Explore key techniques for optimizing and backtesting your strategies to improve their success rate.
• Practical examples of building trading bots without needing any programming knowledge.
Why Attend?
• Free access to expert-level content.
• Learn how to leverage StrategyQuant’s verified templates for faster, more accurate strategy generation.
• Discover how to create high-performance strategies that reduce the need for constant trial and error.
• Improve your understanding of how to trade popular indices effectively, based on technical analysis and advanced algorithmic logic.
Do you want to create more strategies?
Simply subscribe to the StrategyQuant YouTube channel and watch our course series for free in the playlist video by video. Each episode is designed to give you hands-on insights into the world of algo trading.
Data settings
The strategy file stores the settings it was built with (engine MetaTrader4, symbol XAUUSD_M1_UTC2, H1). When you retest it, select your own symbol, engine and costs.