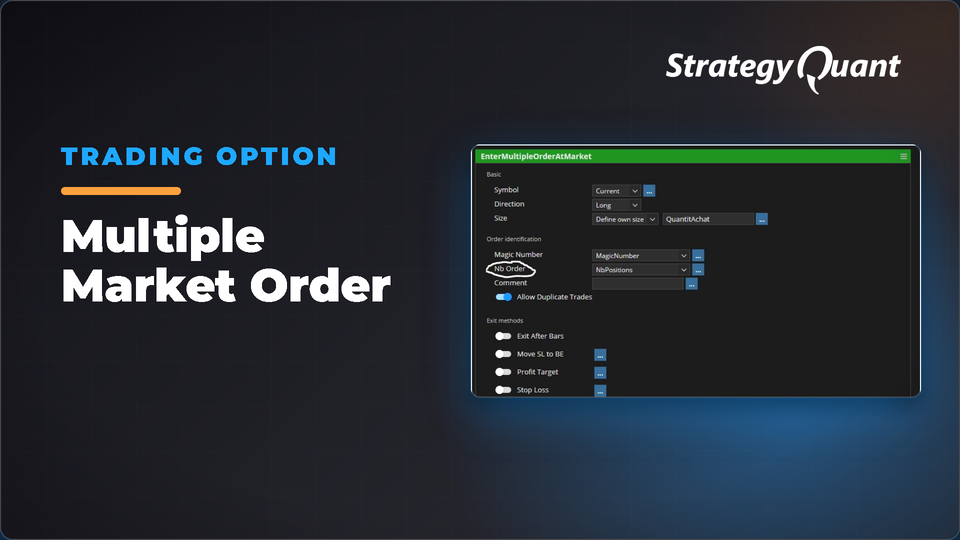
Apre simultaneamente più ordini a mercato con magic number sequenziali, consentendo la chiusura parziale delle posizioni a diversi target di profitto o stop loss. Ideale per strategie di scaling e per la gestione di livelli di rischio multipli.
Snippet Multiple Orders at Market: invia più ordini contemporaneamente con magic number differenti.
Nello screenshot, seleziona il numero di ordini e un magic number. Se selezioni 3 come numero di ordini e 1000 come magic number, verranno creati 3 ordini a mercato con i seguenti magic number: 1000, 1001 e 1002.
Chiudi parzialmente alcuni ordini a mercato su un target di profitto, quindi chiudi gli altri ordini su target di profitto o stop loss differenti.
package SQ.Blocks.Order.Open;
import java.util.ArrayList;
import com.strategyquant.datalib.TradingException;
import com.strategyquant.datalib.UpdateEventTypes;
import com.strategyquant.lib.SQTime;
import com.strategyquant.lib.SQUtils;
import com.strategyquant.tradinglib.*;
// Modified by Emmanuel Evrard for StrategyQuantX Community
@BuildingBlock(name="(MMKT) Enter Multiple Order at market", display="EnterMultipleOrderAtMarket", returnType=ReturnTypes.Order)
@Help("Opens Multiple order at current market price")
public class EnterAtMarketMultiOrder extends ActionBlock
{
    @Parameter(defaultValue="Any", category="Basic", showIfDefault=false)
    @Editor(type=Editors.SelectionSymbolsWithAny)
    public String Symbol;
    @Parameter(defaultValue="1", category="Basic")
    @Editor(type=Editors.Selection, values="Long=1,Short=-1")
    public int Direction;
    @Parameter(category="Basic")
    @Editor(type=Editors.Formula, formulaName="Size")
    @Required
    public IFormula Size;
    @Parameter(defaultValue="MagicNumber", category="Order identification", showIfDefault=false)
    @Help("Magic number is used to identify the first trade, it should be unique for every trade you open.")
    public int MagicNumber;
    @Parameter(defaultValue="Number Of Order", category="Order identification", showIfDefault=false)
    @Help("Number Of Order is used to set the quantity of order, Their MagicNumbers are successives to the above MagicNumber")
    public int NbOrder;
    @Parameter(defaultValue="", category="Order identification", showIfDefault=false)
    public String Comment;
    @Parameter(defaultValue="false", category="Order identification", showIfDefault=false)
    @Help("If set to true, it will allow to place multiple trades with the same Magic Number")
    public boolean AllowDuplicateTrades;
    public ExitMethod[] ExitMethods;
    @Override
    public void OnAction() throws TradingException
    {
        if((!AllowDuplicateTrades || !engineSupportsDuplicateTrades()) && checkLiveOrderExists(0, true) != null)
            return;
        byte orderType = (Direction > 0 ? OrderTypes.Buy : OrderTypes.Sell);
        double sl = computeSL(orderType, (Direction > 0 ? Strategy.MarketData.Chart(Symbol).Ask() : Strategy.MarketData.Chart(Symbol).Bid()));
        double size = computeSize(orderType, 0, sl);
        ATM atm = Strategy.getATM();
        double pt = computePT(orderType, (Direction > 0 ? Strategy.MarketData.Chart(Symbol).Ask() : Strategy.MarketData.Chart(Symbol).Bid()));
        int MagicNumber1 = MagicNumber;
        for(int i = 0; i < NbOrder; i++)
        {
            MagicNumber = MagicNumber1 + i;
            if(atm != null && atm.isApplicable(Strategy, size, sl, orderType)) {
                openATMOrder(atm, -1, size, sl, pt, orderType, 0);
            } else {
                openNormalOrder(-1, size, sl, orderType, 0);
            }
        }
    }
    protected void openNormalOrder(double openPrice, double size, double sl, byte orderType, int barsValid) throws TradingException {
        ILiveOrder order = Strategy.Trader.Open(orderType, Symbol, openPrice)
                .setSize(size).setMagicNumber(MagicNumber).setComment(Comment).Send();
        if(order.isSuccessful()) {
            handleBarsValid(order, barsValid);
            for(ExitMethod exitMethod : ExitMethods) {
                if(!order.isClosedOrder()) exitMethod.setForOrder(order, Strategy);
            }
        }
    }
    protected double computeSL(byte orderType, double orderPrice) throws TradingException {
        ExitMethod slExit = getStopLossExit();
        return slExit == null ? Order.NOT_DEFINED : SQUtils.fixPrice(Strategy.getInstrumentInfo().tickStep, slExit.computeValue(orderType, Strategy, Symbol, orderPrice));
    }
    protected double computePT(byte orderType, double orderPrice) throws TradingException {
        ExitMethod ptExit = getProfitTargetExit();
        return ptExit == null ? Order.NOT_DEFINED : SQUtils.fixPrice(Strategy.getInstrumentInfo().tickStep, ptExit.computeValue(orderType, Strategy, Symbol, orderPrice));
    }
    private ExitMethod getStopLossExit() {
        for(ExitMethod e : ExitMethods) if(e.getExitType() == ExitTypes.StopLoss) return e;
        return null;
    }
    private ExitMethod getProfitTargetExit() {
        for(ExitMethod e : ExitMethods) if(e.getExitType() == ExitTypes.ProfitTarget) return e;
        return null;
    }
    protected double computeSize(byte orderType, double price, double sl) throws TradingException {
        return ((MMFormulaBlock) Size).computeSize(Strategy, Symbol, orderType, price, sl);
    }
    protected ILiveOrder checkLiveOrderExists(int direction, boolean includeClosingOrders) {
        for(int i=Strategy.Trader.getOpenOrdersCount(includeClosingOrders)-1; i>=0; i--) {
            ILiveOrder order = Strategy.Trader.getOpenOrder(i, includeClosingOrders);
            if(order.isMarketOrder() && OrderFunctions.identify(order, Strategy, Symbol, direction, MagicNumber, Comment))
                return order;
        }
        return null;
    }
    protected boolean engineSupportsDuplicateTrades() { return Strategy.Trader.supportsDuplicateTrades(); }
    protected void handleBarsValid(ILiveOrder order, int barsValid) throws TradingException {}
}